
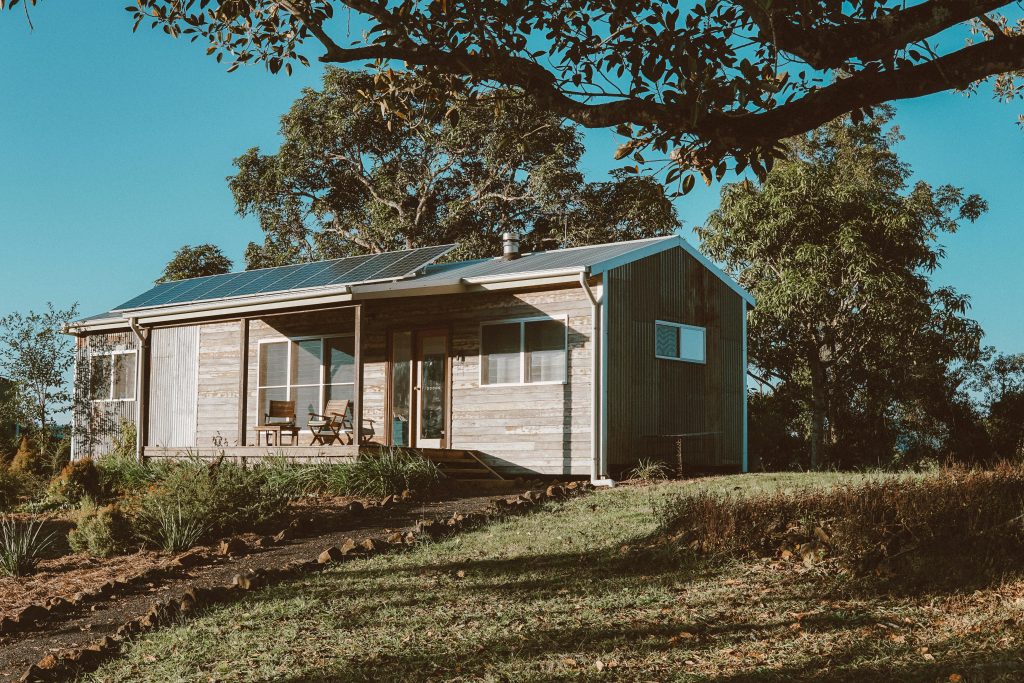

I recently bought a house! And I learned A LOT. Today I’m sharing what I wish I knew before buying a house, my experience with buying a house as an unmarried, self-employed woman, and some insights on the numbers involved in my home buying process.
Some background: I recently purchased my home by myself, which means my partner, T-Bone, is technically my tenant. If you’re curious about how we reached that decision, the financial implications, what he pays in rent, and how we’re both protected, I’ve got a Patrons-only post that dives deep into all those juicy details.
The Motivation Behind My Decision
So, why did I want to buy a house? The journey began about ten years ago, in December 2014, when I got serious about my financial life. I made a commitment to pay off my student loans and started saving for a house. At first, I put away just $10 in a savings account, but that small act symbolized my promise to myself that one day I would own a home.
Having a house has been a long-standing obsession for me. Despite always having stable housing, I’ve lived with the anxiety of potentially losing that security. Even as I paid off my student loans and invested in the stock market, the desire to buy a house remained at the back of my mind. As a 36-year-old unmarried woman in a committed relationship with T-Bone for nearly 11 years, I faced the unique challenge of balancing our relationship dynamics with my desire for homeownership.

Homeownership as a Form of Protection
For me, buying a house on my own was about protection. Being the sole owner means T-Bone can’t claim it in the unfortunate event we were to separate. My name is on the mortgage and the deed, which adds a layer of security. If we break up, I have a place to live independently. Owning this home alleviates my fears of potential homelessness and a stable financial future.
The Process of Buying a Home as a Self-Employed Woman
I must admit, I was intimidated by the process of buying a house. As a self-employed individual without a W2 job since 2019, I thought it would be a nightmare. However, it turned out to be more manageable than I anticipated.
My journey began while still living in North Carolina. I scoured Redfin daily for homes in Massachusetts and sent listings to a local realtor. I didn’t see the house I ultimately bought until after my offer was accepted. It was a risky move, and if I could do it again, I wouldn’t recommend it—always try to tour a house in person if you can!
Finding My Home
After a bit of luck, I found a house that met my criteria and sent my realtor an email. Unfortunately, just after we decided to make an offer, another offer was accepted. However, that offer fell through, and I quickly jumped back into the fray, submitting my offer at asking price.
What contributed to my success? A solid buyer profile. With an excellent credit score over 800 and minimal debt (only some medical debt that doesn’t show up on my credit report), I presented myself as an attractive candidate. After ten years of saving, I had $80,000 in cash, which gave me a comfortable down payment cushion.
The Financial Breakdown
Ultimately, I purchased a two-bedroom, one-bathroom home with 690 square feet for $300,000. Yes, that’s a significant amount for a relatively small space, but welcome to the 2024 Massachusetts housing market. I put down 10%, or $30,000, and my closing costs were $9,925.
Despite the costs, I understood that owning a home involves ongoing expenses beyond the mortgage. From property taxes to maintenance and unexpected repairs, it’s crucial to budget for these additional financial responsibilities. I learned this firsthand when I had to address several repairs soon after moving in.

What I Wish I Knew Before Buying a House:
Reflecting on my journey, here’s what I wish I had known before buying a house:
Tip 1: Spend Less Than You’re Approved For:
Just because the bank approves you for a high amount doesn’t mean you should spend it all. Assess what you can truly afford when considering mortgage payments, property taxes, and insurance. You’ll also need to factor in repairs and home maintenance costs.
Tip 2: Understand the Market
Buying in a competitive area can mean making compromises, whether on price or other factors. My purchase felt like an overpayment, but given the current market dynamics, I knew it was necessary to act quickly.
Tip 3: Shop Around for Interest Rates
I worked with one loan officer and ended up with a high interest rate because I didn’t shop around. Don’t feel guilty about exploring options; it’s your financial future at stake.
Final Thoughts
Owning a home is more than just having a place to live—it’s a significant financial commitment. My experience taught me invaluable lessons about budgeting, planning for the unexpected, and staying true to my values.
I hope sharing my journey and what I wish I knew helps you in your own homebuying adventure. The process can be daunting, but with careful planning and a clear understanding of your priorities, it can be fulfilling too.
I share more details and thoughts in a recent YouTube video. Check it out below:


